

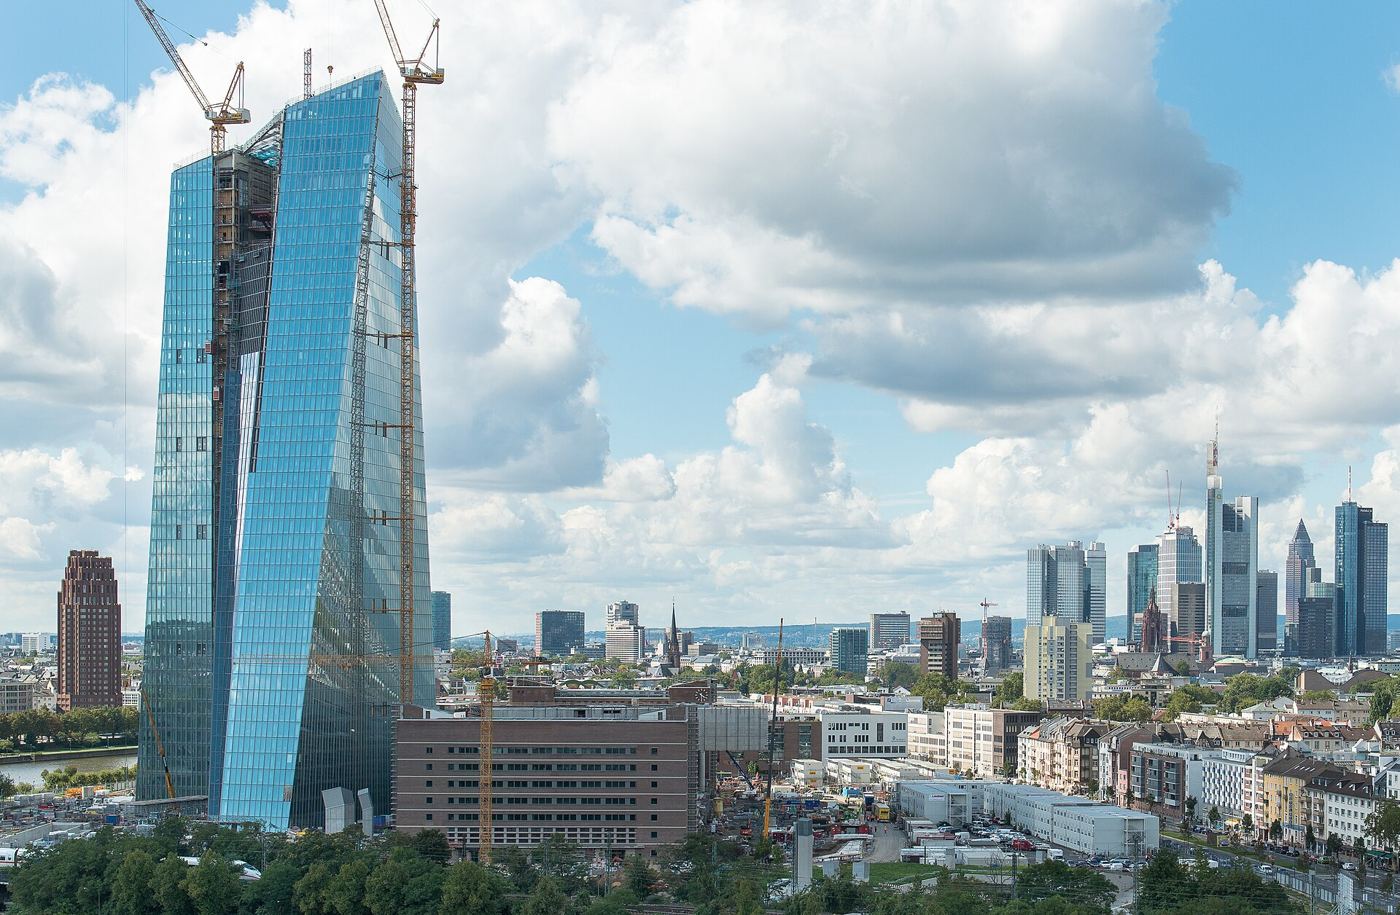
The European Central Bank has held its key interest rate steady while its president prepares to leave the job early, closing a chapter for the eurozone’s central bank. On 29 October 2026 the Governing Council kept the deposit rate at 2.5 percent, after raising it by a quarter point in September, and President Christine Lagarde said the council had debated whether a further rise was appropriate before deciding unanimously to wait for more information. Euro-area inflation had climbed to 4 percent in October, its highest in more than three years, driven mainly by energy costs. At the same time, the ECB announced that Lagarde will step down on 7 February 2027, months before the formal end of her mandate, so the December meeting will fall in her final weeks in office. Markets now price a strong chance of a rise to 2.75 percent at that meeting.
What the Evidence Shows
The decision leaves eurozone borrowers and savers in a holding pattern, with the next move depending on data that arrives before 17 December. Bundesbank President Joachim Nagel said in mid-November that another rise was highly probable if conditions did not change, and other policymakers have signalled the same direction. For households with variable-rate mortgages, a December rise would mean higher monthly payments, while savers could see modestly better returns. Lagarde has stressed that the surge in prices is mainly energy-led, and that the bank will follow a data-dependent, meeting-by-meeting approach rather than pre-committing to a path. Whoever succeeds her will inherit the same dilemma: inflation above target, growth under pressure, and a council that must choose between the two. The transition also comes at a sensitive moment for the euro, with currency markets watching every hint about the timing and size of the next move. Reporting and analysis from sources such as World Bank track the same developments, and specialists following ECB rate hold say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, ECB rate hold matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for ECB rate hold hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
