

Climate Risk Is Rewriting the Price of Home Insurance
Home insurance used to be the dullest line in the household budget: a yearly renewal, a modest premium, a risk pooled so widely that individual streets barely mattered. Climate change is ending that arrangement. As floods, storms, wildfires and subsidence intensify, insurers are repricing risk address by address, raising premiums sharply in exposed places, adding conditions, or withdrawing cover altogether. The mortgage market, which depends on insurable homes, is watching nervously.
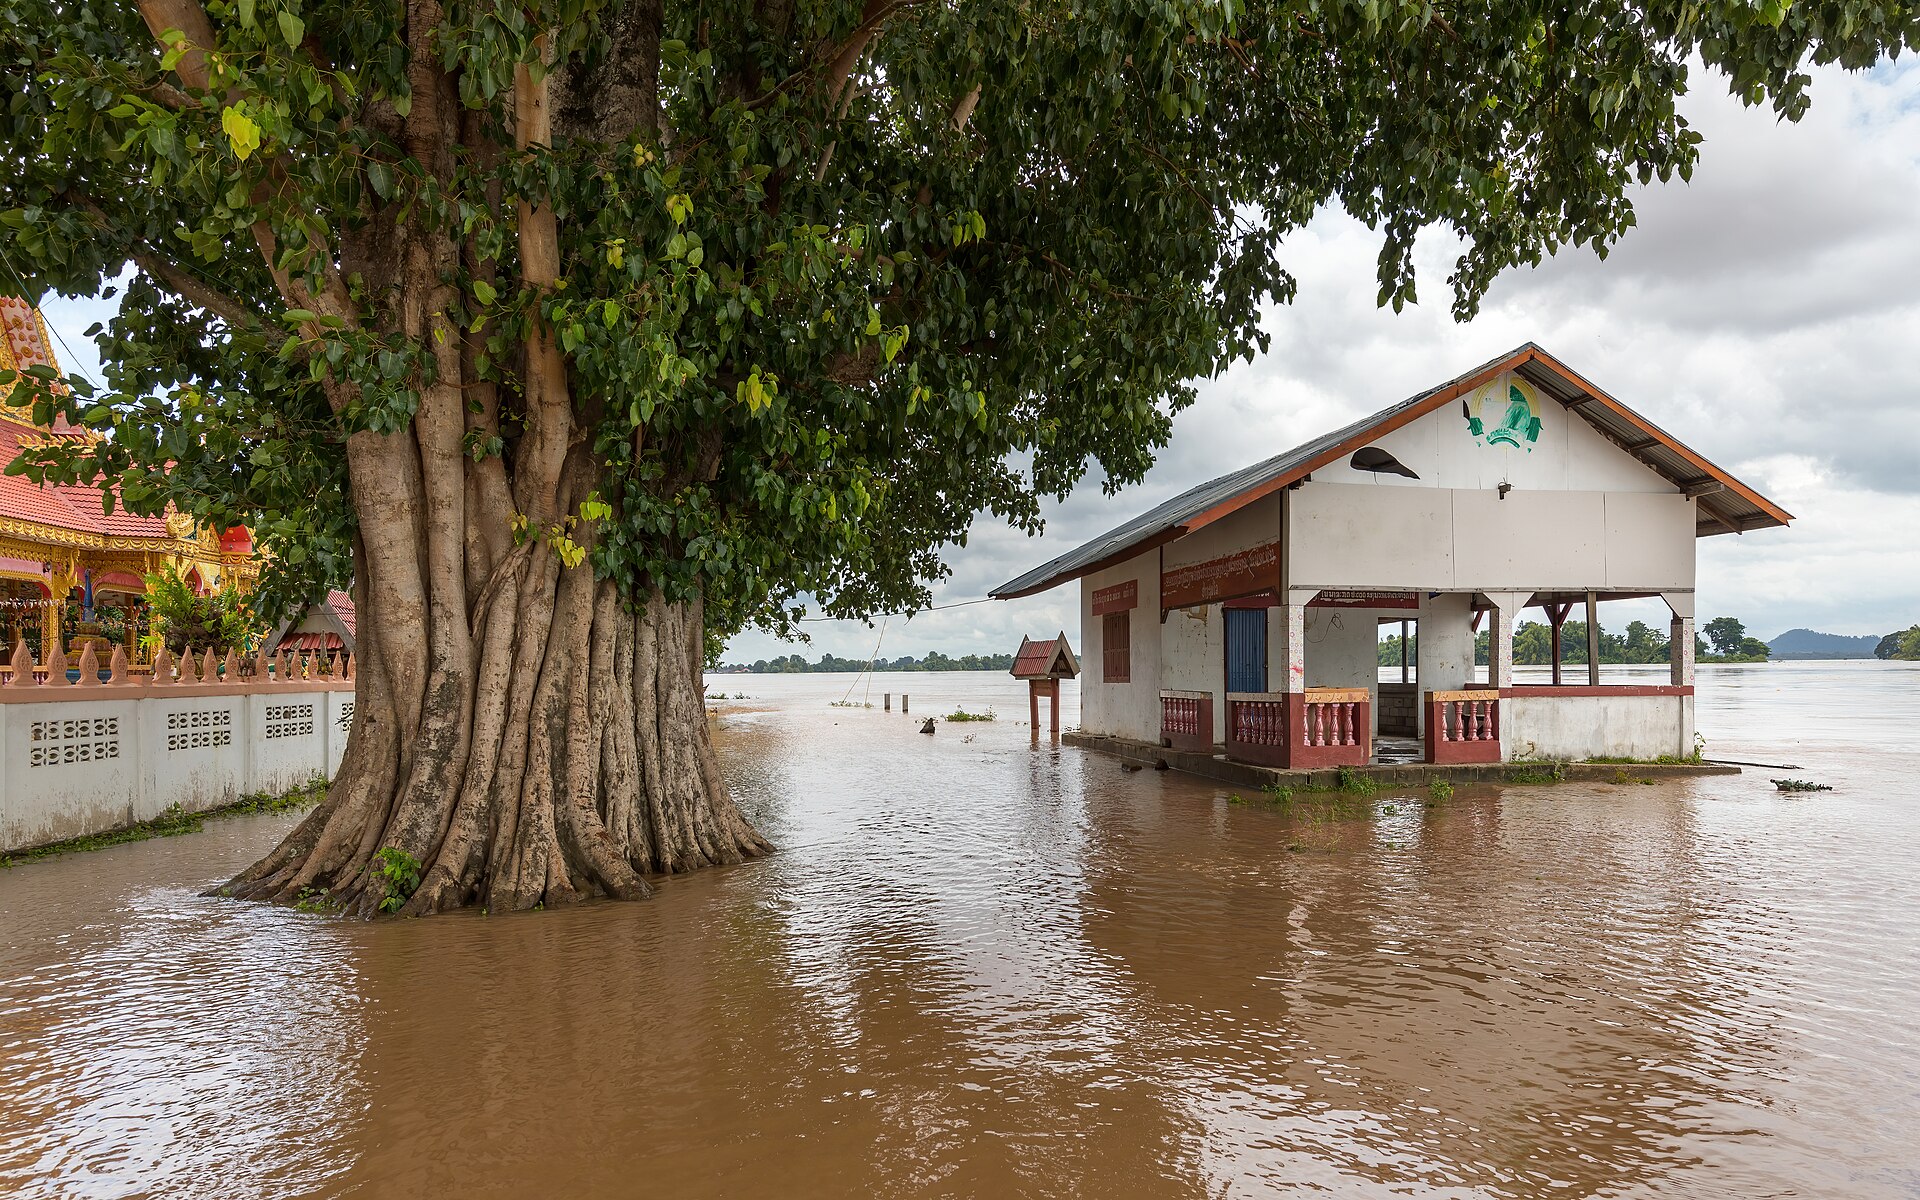
The mechanics are straightforward. Insurance works when losses are predictable in aggregate and independent in practice; one house burns, the pool pays. Climate-driven perils break both comforts: a single flood or storm surge damages thousands of insured homes at once, and the past is becoming a weaker guide to the future. Reporting by the BBC on flooded communities has shown the human version of the spreadsheet: families quoted premiums exceeding their mortgage payments, or offered renewal only with flood excluded, which is to say, with the point removed.
When Cover Disappears, Value Follows
The deepest problem is not expensive insurance but absent insurance. In parts of the United States, Australia and elsewhere, major insurers have stopped writing new policies in high-risk zones, leaving state-backed schemes of last resort to swell beyond their design. An uninsurable home is hard to mortgage and harder to sell at full value, so climate risk converts directly into housing wealth losses, concentrated on owners least able to absorb them. Our blog has followed this protection gap as it widens from a pricing story into a financial stability question.
Regulators are caught between two duties: premiums must reflect risk if insurers are to remain solvent, yet risk-reflective pricing can strand communities. The Bank of England, which stress-tests insurers and banks against climate scenarios, has pressed firms to model physical risk properly rather than discover it claim by claim. Britain’s Flood Re scheme offers a different template: a levy-funded pool that caps flood premiums for eligible homes while funding and incentivising resilience measures, explicitly buying time for adaptation rather than pretending the risk away.
Adaptation Is Becoming an Insurance Product
A constructive shift is under way in how cover responds to prevention. Insurers increasingly discount or require resilience: flood doors and raised electrics, fire-resistant roofing and cleared vegetation, water butts and permeable drives that slow runoff. Parametric products, paying a fixed sum when a measured trigger such as river height is breached, promise faster help without loss-adjusting delays. Councils and developers, meanwhile, face stricter questions about building homes in places the water has already claimed once.
None of this removes the underlying arithmetic: risk that keeps rising must be paid for by someone, through premiums, taxes, adaptation spending or losses. The policy argument is about sharing it fairly and reducing it fastest, by defending the defensible and, in the hardest-hit places, planning honestly for retreat.
What Homeowners Can Do Before Renewal
Households are not powerless in the repricing. Documenting resilience measures, from flood barriers and non-return valves to roof condition and cleared gutters, increasingly earns premium recognition, and photographs cost nothing. Shopping beyond the incumbent insurer matters more each year as risk models diverge; two firms can price the same street very differently. Owners in areas with collective defences should make sure their insurer knows it, because models sometimes lag completed schemes. Renters, often forgotten in the debate, should note that contents cover faces the same repricing and that a landlord’s buildings policy does not protect a tenant’s possessions. None of this rivals public investment in defences, but at renewal time, evidence is the only language the market reliably rewards. You can follow the latest reporting on this and related subjects on our front page, which is updated throughout the day.
Insurance is society’s early-warning system for risk, priced in pounds rather than press releases. Its new message is unambiguous. The cost of a changing climate is arriving at individual addresses, and the cheapest time to act on drainage, defences and building standards was before the renewal quote made the argument at the kitchen table.
