

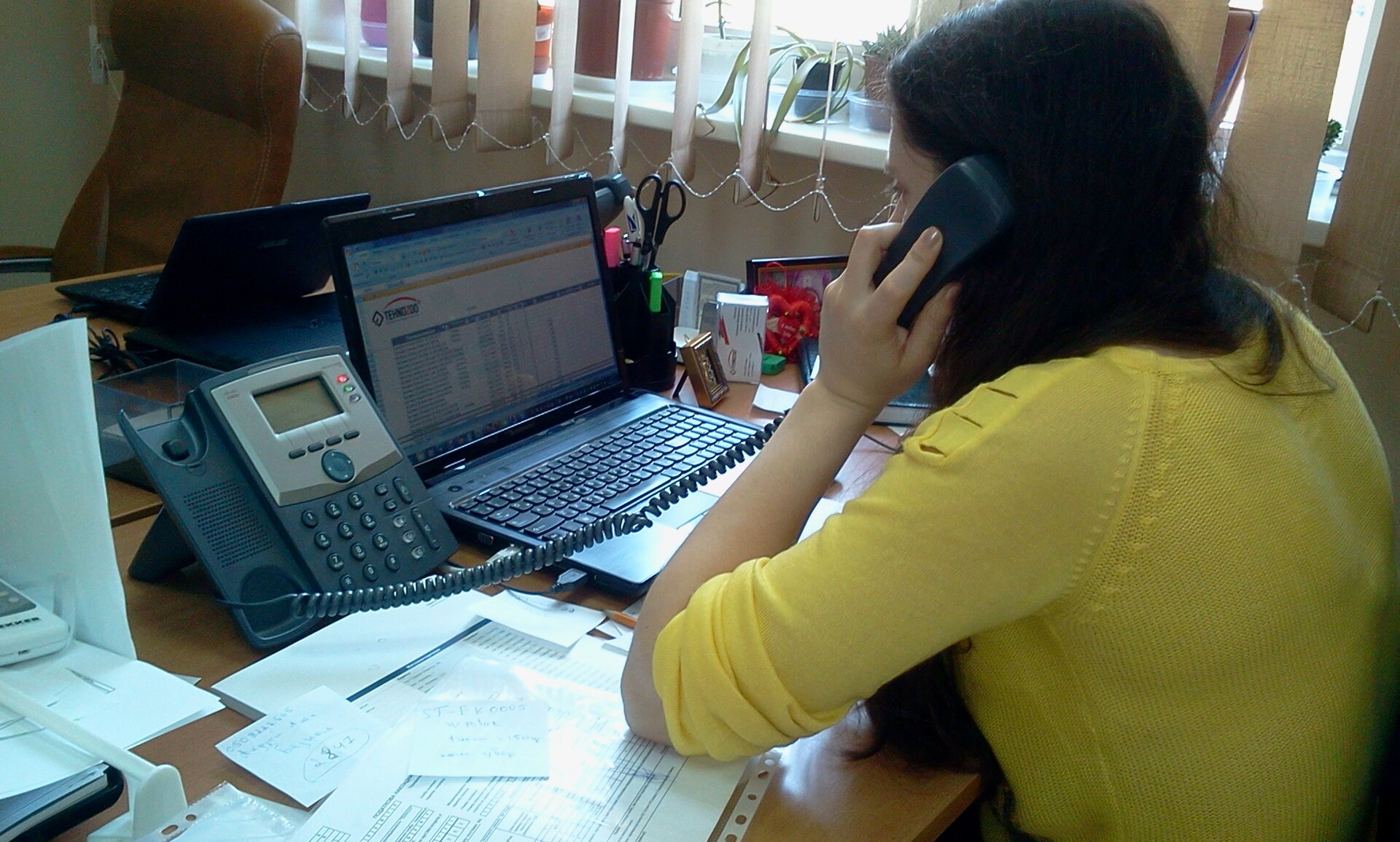
When a business begins accepting digital asset payments, the person who feels the change most is often not the owner but the finance worker reconciling the books at a laptop. Each crypto receipt arrives with a transaction reference instead of a card batch number, its value in conventional currency depends on the exact time it was received, and network fees must be recorded separately. Finance teams are developing careful routines for this work: converting values at a consistent, documented rate, matching every transaction to an invoice, and keeping wallet records aligned with the accounting software so that month-end closes without a pile of unexplained differences waiting for attention. Training matters as well, because staff who understand what a transaction hash is, and where to verify it, make fewer errors and spot unusual activity considerably earlier in the process.
What the Evidence Shows
Accountants note that good records matter beyond tidy bookkeeping. Tax authorities in most countries expect businesses to know what was received, when, and what it was worth, and auditors ask the same questions. Many firms simplify life by using a payment processor that converts receipts to regular currency immediately and provides standard reports, while others that hold digital assets add regular balance checks between wallet and ledger. Clear separation between company wallets, written procedures for who may authorise transfers, and a monthly review of small discrepancies before they grow are becoming standard practice. The technology may be new, but the principle is the oldest in finance: every unit of value must be accounted for. Over time, these routines become unremarkable, which is precisely the point: digital asset income takes its place in the ledger alongside cards and bank transfers, fully documented and auditable. Reporting and analysis from sources such as European Central Bank track the same developments, and specialists following reconciling digital asset payments say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a sector being absorbed, piece by piece, into the regulated financial mainstream. Work on reconciling digital asset payments now happens under licensing regimes, audit expectations and consumer-protection rules that would have been unrecognisable a few years ago. Long-standing participants are divided between relief at the legitimacy and regret for the experiment’s wilder freedoms.
What Happens Next
What happens next for reconciling digital asset payments will be shaped by the interaction of regulation, market appetite and the sector’s own capacity for self-inflicted wounds. The infrastructure is more professional than it was, the rules are clearer, and the remaining question is whether growth can stay boring. Participants with the longest memories say boring would be the real milestone. You can follow related developments in our coverage of crypto.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
